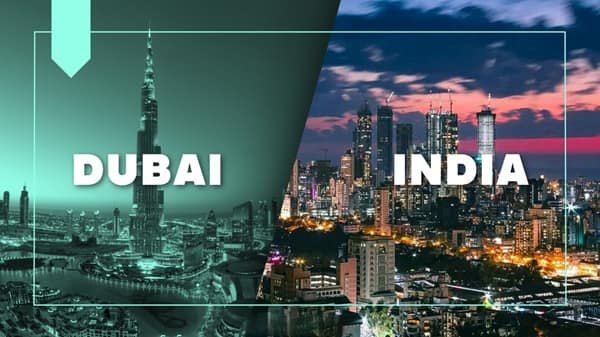
Dubai and India attract property investors for very different reasons. Dubai offers an internationally connected property market with designated freehold areas, a large expatriate population, and investment opportunities across luxury apartments, waterfront homes, and rental properties. India, meanwhile, has a much larger and more diverse housing market, ranging from affordable urban apartments to premium residences, plotted developments, and commercial real estate.
For buyers comparing the two destinations, the differences extend beyond property prices. Ownership rules, taxes, rental demand, financing, transaction costs, and market risks can all influence the final investment outcome.
1. Property Ownership Rules and Foreign Investment
One of Dubai’s defining features is its openness to international property buyers. Foreign nationals can purchase freehold property in designated areas, where ownership rights generally include the property and associated land rights, subject to the applicable legal framework.
Popular locations such as Dubai Marina, Downtown Dubai, and Palm Jumeirah attract international buyers seeking residential homes or investment properties. However, ownership rights depend on the specific location and property designation, so buyers must verify the legal status of the asset before purchasing.
India has a different ownership framework. Indian citizens can purchase residential and commercial properties subject to applicable laws, while foreign nationals and Non-Resident Indians (NRIs) face specific rules depending on their citizenship, residential status, and the type of property.
For example, NRIs and eligible persons of Indian origin can generally purchase residential and commercial property in India, but agricultural land, plantation property, and farmhouses are subject to restrictions. Foreign citizens who are not eligible under the applicable rules may face additional limitations.
The practical difference is that international buyers in Dubai often begin by identifying an eligible freehold area, whereas property ownership in India requires careful attention to the buyer’s legal status and the property’s documentation.
2. Market Size, Property Choices, and Investment Activity
Dubai has developed a strong international reputation as a property investment destination. Its market includes luxury residences, high-rise apartments, villas, branded residences, holiday homes, and large mixed-use developments.
The scale of recent activity reflects this appeal. According to Dubai government figures published in January 2026, the emirate recorded more than 270,000 real estate transactions worth AED 917 billion during 2025. <Cite refs={[“turn184596search0”]}/>
India’s property market operates on a much broader geographical scale. Investors can choose among metropolitan cities such as Mumbai, Bengaluru, Delhi-NCR, Hyderabad, Chennai, and Pune, as well as smaller cities and emerging urban centres. Prices, rental demand, infrastructure quality, and property types can vary considerably between locations.
This creates two distinct investment experiences. Dubai offers access to a concentrated international market, while India provides a much wider range of local markets, buyer segments, and price points.
Neither market should be judged by headline transaction values alone. Investors need to compare individual neighbourhoods, property types, and realistic purchase budgets.
3. Property Prices and Rental Income
Dubai is often associated with premium real estate, but its market includes properties at different price levels. The cost of an apartment depends on its location, building quality, views, amenities, age, and proximity to transport or business districts.
Rental demand is supported by expatriate residents, professionals, businesses, and tourism. This can create opportunities for both long-term residential rentals and eligible short-term holiday rentals.
India also offers rental opportunities, particularly near employment hubs, universities, business districts, and transport corridors. However, rental yields and tenant demand differ widely between cities and neighbourhoods.
An investor should distinguish between gross rental yield and net return. Gross yield compares annual rental income with the purchase price. Net return also accounts for service charges, repairs, vacancy periods, management fees, insurance, and other expenses.
Dubai’s official 2024 real estate report highlighted rental yields as an attraction for investors, but actual returns vary by property and location. <Cite refs={[“turn184596search24”]}/> Buyers should calculate their own expected income instead of assuming that every property will produce a high yield.
4. Taxes and Transaction Costs
Tax treatment is another important difference between the markets.
Dubai does not generally impose an annual residential property tax comparable to those found in many other countries. However, buyers may pay property registration and transfer fees, while owners can face service charges, maintenance expenses, and other property-related costs. Rental arrangements may also involve applicable municipal fees and regulatory requirements.
India has a different cost structure. Buyers generally need to budget for stamp duty and registration charges, which vary by state and transaction circumstances. Property owners may also pay municipal property tax and incur society maintenance charges.
Rental income and gains from selling property can have income tax implications in India, subject to applicable rules, exemptions, and the taxpayer’s circumstances.
Dubai’s relatively different tax environment can be attractive, but Indian investors should also consider their own tax residency and reporting obligations. Owning property abroad does not automatically remove tax responsibilities in India or another country.
5. Regulations and Transaction Transparency
Dubai has a centralised real estate regulatory ecosystem involving the Dubai Land Department and the Real Estate Regulatory Agency (RERA). Buyers can use official channels to check transaction information, verify relevant project details, and review applicable registration procedures.
India also has regulatory protections, particularly through the Real Estate (Regulation and Development) Act, 2016, commonly known as RERA. However, implementation and administration operate through state and union territory authorities. Buyers must check the relevant state’s project registration records and local requirements.
In both markets, regulatory systems do not eliminate every risk. A buyer should independently verify title, approvals, payment schedules, developer credentials, service charges, and possession terms.
Off-plan purchases deserve particular attention. Payment plans and potential appreciation can look attractive, but buyers must understand construction timelines, project registration, refund conditions, and the financial consequences of delays.
6. Financing, Currency, and Investment Risk
Financing conditions can materially change an investment’s affordability. Dubai buyers may obtain mortgages from eligible lenders, but approval depends on residency status, income, creditworthiness, down payment, and the property’s eligibility. Non-resident buyers may face different lending conditions from UAE residents.
India has its own home-loan market, with eligibility and rates depending on the lender, borrower profile, and loan type. Indian buyers purchasing property abroad must also consider the rules governing overseas remittances and the currency in which the property and rental income are valued.
Currency risk is especially relevant for an Indian investor buying in Dubai. Property prices, rent, and many expenses are denominated in UAE dirhams, while the investor may earn income in Indian rupees. Exchange-rate movements can affect the investment’s overall return when converted back into rupees.
Both markets can experience price corrections, oversupply, interest-rate changes, and weaker rental demand. Diversification and careful financial planning remain important regardless of the destination.
7. Which Market Is Better for Investors?
Dubai may suit investors seeking international exposure, access to a globally connected city, and rental opportunities linked to expatriate demand and tourism. It can also appeal to buyers who intend to live in the UAE.
India may be more appropriate for investors who understand local markets, want to buy closer to family or business interests, or prefer investments aligned with their long-term plans in the country.
The decision should depend on the individual property rather than the destination’s reputation. Compare total acquisition costs, realistic net rental income, financing terms, taxes, legal requirements, and resale prospects before committing funds.
Conclusion
Dubai and India offer distinct real estate opportunities. Dubai stands out for its international buyer base, designated freehold ownership areas, and globally connected property market. India offers a much larger and more geographically diverse market, with opportunities across multiple price segments and cities.
Neither destination guarantees appreciation or rental income. The stronger investment is the one whose costs, legal requirements, expected returns, and risks match the buyer’s financial goals. Careful due diligence matters more than choosing a market simply because it is currently popular.